Third video call. The vibe is good.
You both like chai over coffee, long drives, and making fun of your dads’ WhatsApp forwards.
Then they ask, very casually: “So… any loans?”
And suddenly your brain is flashing your credit card bill, that personal loan from 2023, and the ₹40,000 you still owe your college friend for the Goa trip.
Sharing your full financial situation before marriage feels like handing over your phone with no screen lock. Scary. Exposing. Slightly sweaty.
This post tells you what to share, when to share it, and the exact words to use. Think of it as the follow-up to our five money questions to ask before marriage, but this time the spotlight is on your wallet.
The Short Answer: Yes, the Full Picture (Just Not on Call One)
Verdict: your future spouse should know your complete financial situation before the wedding.
Not your UPI PIN. Not every Swiggy order. But the big stuff, yes.
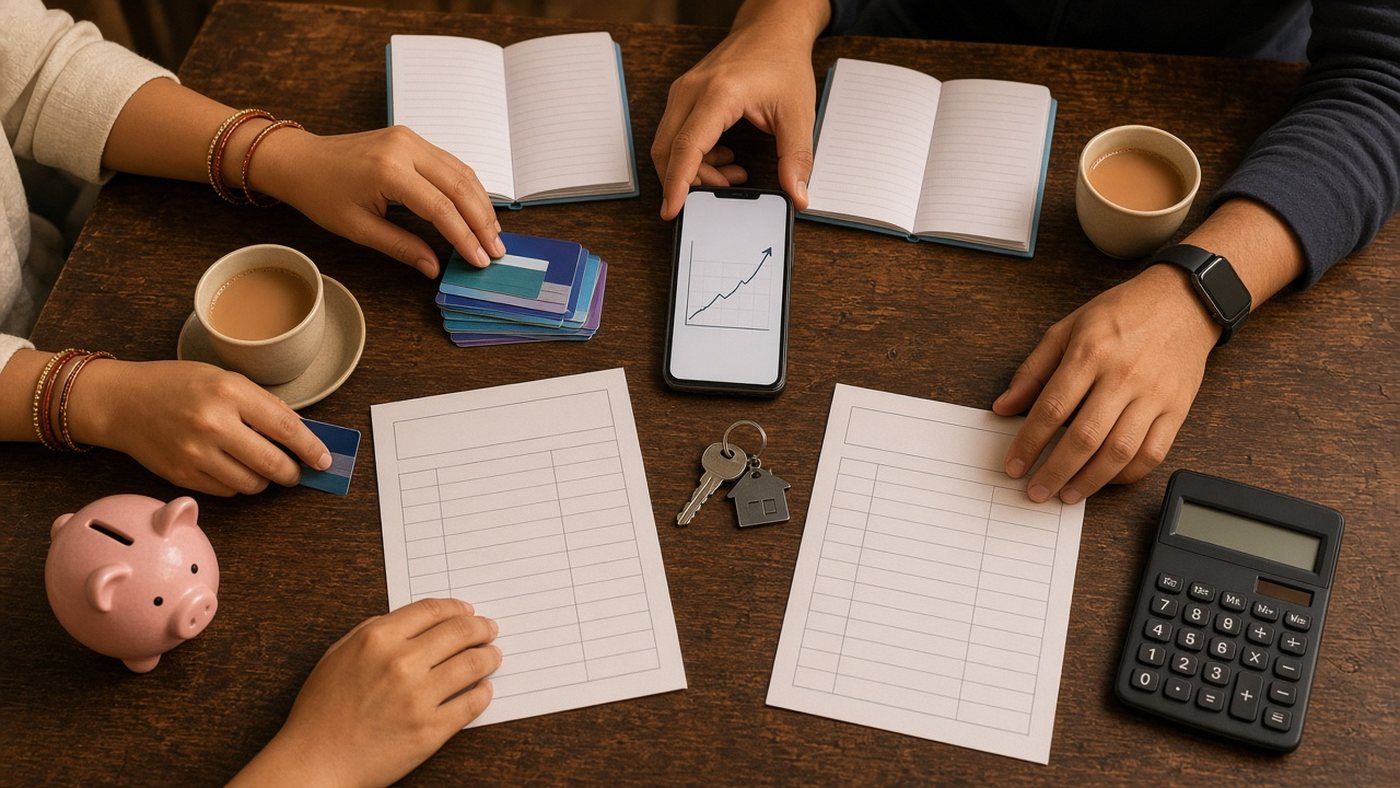
Marriage merges more than two families and two sets of steel utensils. It merges two money stories. Rent, EMIs, savings, parents’ medical bills. All of it lands on one shared table.
The trick is timing. Nobody needs your bank statement on the first chat. Whether you reveal your exact salary on a matrimony profile is a separate question. Full disclosure is for when things are getting serious.
Awkward for 10 minutes beats awkward for 10 years.
What Your “Complete Financial Situation” Actually Includes
Most people think it just means salary. It doesn’t. Here’s the full list:
- Income: take-home pay, bonuses, side hustles, rental income.
- Savings and investments: FDs, mutual funds, PF, that one stock you bought because a reel told you to.
- Debts: education loan, car loan, personal loan, credit card balance, money borrowed from friends.
- Family duties: do you send money home every month? Support a sibling’s studies? Pay for a parent’s treatment?
- Credit health: a rough idea of your credit score, and any past defaults.
- Big plans: a house, an MBA, a startup, a sabbatical in the hills.
Family duties matter more than people admit. They often decide whether you can afford a joint family vs nuclear family setup after the wedding.
Pro tip: Write these six points in your notes app before the talk. You will forget the car loan otherwise. Everyone forgets the car loan.
Why Hiding Money Stuff Always Backfires
Meet Karan. 31. Great job, great jawline, great at dodging questions.
Karan had a ₹6 lakh personal loan. He planned to “clear it quietly” before the wedding. He didn’t.
Three months after the shaadi, his wife Neha opened the courier. Loan recovery letter. Bold font. Very rude.
The loan wasn’t the real problem. Couples handle loans every day. The secret was the problem. Neha’s first thought wasn’t “how do we pay this?” It was “what else hasn’t he told me?”
Hidden money stuff surfaces in the worst ways:
- A loan application gets rejected because of a low credit score.
- A relative mentions the “help” you send home every month.
- The wedding budget blows up and nobody knows who’s paying.
Honesty also shows you who’s really in it with you. If someone is fine with you earning less, they’ll say so. Many people happily marry someone with a much lower salary when everything is out in the open. It’s the surprises they can’t forgive.
When to Share Your Financial Situation Before Marriage
Disclosure works best in layers. Here’s a simple timeline:
| Stage | What to share |
|---|---|
| First few chats | Job, rough income range, general money values |
| Both clearly interested | Savings habits, family duties, any major loans |
| Before roka or fixing dates | Exact numbers: debts, EMIs, savings, credit score |
| Before the wedding | Who pays for what, joint account plans, big goals |
The rule is simple. Share before families make it official. Telling someone about a big loan after the roka feels like a trap, even if you didn’t mean it that way.
It’s the same logic as deciding when to tell your match about your past. Early enough to be fair. Late enough that it’s actually their business.
And please do it before the wedding spending starts. Going through a wedding planning checklist for Indian weddings is much easier when both of you know what’s in the bank.
How to Have the Money Talk Without It Feeling Like an Income Tax Raid
Money talk goes wrong when it feels like an interrogation. So make it a swap, not a raid.
1. Go First
Share your own numbers before asking for theirs. It lowers the guard instantly.
What to say: “Before things get more serious, I want you to know where I stand with money. I have an education loan with about two years left. I also send some money home every month.”
2. Ask, Don’t Audit
Skip “show me your CIBIL score.” Try curiosity instead.
What to say: “How do you usually handle money? Are you a saver or a spender? I’m a saver who loses all self-control during sales.”
3. Talk Values, Not Just Numbers
Two people earning the same can live very differently. One saves 40%. The other buys a new phone every Diwali.
Money values sit right at the top of the uncomfortable questions every couple should discuss before marriage. Treat this as one part of that bigger talk.
4. Keep the Families Out (For Now)
This talk is between the two of you. The moment Papa joins with “package kitna hai?”, it becomes a negotiation. Have it alone first. Bring families in later, with a shared story.
What You Can Keep Private (Yes, Some Things)
Complete doesn’t mean every rupee. You’re getting married, not filing an audit report.
It’s fine to keep these to yourself for now:
- Small personal spends, like your secret love of overpriced cold coffee.
- Exact account logins and passwords.
- Your parents’ or siblings’ finances, unless they affect you directly.
- Gifts or savings you plan to keep personal, as long as you say they exist.
The line is easy. If it affects your shared future, share it. If it’s just your chai budget, relax.
Red Flags and Green Flags During the Money Talk
How someone reacts tells you a lot. Watch closely.
🚩 Red flag: They refuse to share anything but want all your details. Or they get angry, vague, or keep “changing the topic to biryani.”
✅ Green flag: They share openly, admit their own mess, and ask “how do we handle this together?”
Secrecy about money sits comfortably among the red flags you should never ignore in an arranged marriage. One dodge is nerves. A pattern of dodging is an answer.
And if they reveal a big debt? Don’t panic. Ask how it happened, what the plan is, and whether they’re sticking to it. A person paying off a loan steadily is far safer than a person hiding one.
In the end, you decide what you can live with. Just decide with the full picture.
Keep Reading
- Should Salary Be Discussed on the First Matrimony Call?
- Should Men Mention Their Salary in Their Matrimony Bio?
- Should Women Mention Career Expectations Before Marriage?
Quick Takeaway
- Yes, your partner should know your complete financial situation before marriage.
- Share in layers: income range early, exact debts and savings before the roka.
- Complete means income, savings, debts, family duties, credit health and big plans.
- Go first, ask with curiosity, and keep families out of the first talk.
- Secrecy is the deal-breaker, not the debt.
FAQs
Should you disclose your financial situation before marriage?
Yes. Your future spouse should know your income, savings, debts and family money duties before the wedding. You can share it in stages, but the full picture should be out before families make it official.
When should I tell my partner about my debt?
Once you both clearly want to move forward, and before the roka or fixing dates. Telling them after the engagement can feel like you hid it on purpose.
Is it okay to keep some money matters private in marriage?
Yes. Small personal spends, passwords and money you plan to keep personal can stay private. Anything that affects your shared future, like loans or monthly support to family, should be shared.
What if my partner refuses to share their finances?
Ask why, gently, and share yours first. If they keep dodging while asking about your money, treat it as a serious warning sign before you commit.
Is a partner’s debt a reason to say no to marriage?
Not by itself. What matters is how the debt happened, whether there is a repayment plan, and whether they were honest about it.
Money talk is awkward. Money secrets are worse.
Have the conversation over chai, with honesty and a little humour. The right person will hear “I have a loan” and reply “cool, let’s make a plan.”
Know a friend quietly hiding a credit card bill from their match? Send this their way. And tell us in the comments: how much did you share before saying yes?
Add a comment