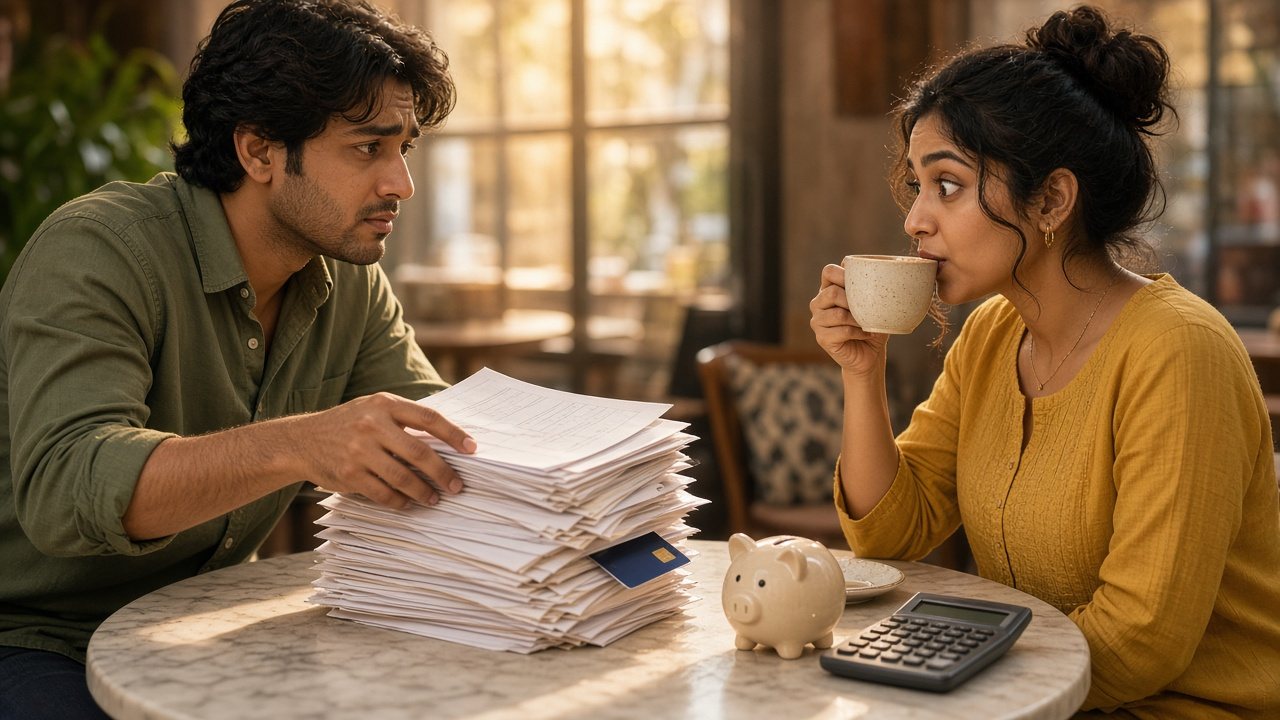
Fourth chai date. Things are going great.
Same taste in old Bollywood songs. Same hatred for people who send voice notes longer than two minutes.
Then they put down the cup and say: “Before this goes further… I have a loan. A big one.”
Your brain instantly opens a calculator app. Your heart is still humming “Tum Hi Ho”.
So, would you marry someone with debt? This post gives you a clear way to decide: which debts are fine, which ones are warning signs, and the exact questions to ask. If you’re on the other side of the table, read our guide on how much of your financial situation to share before marriage too.
The Short Answer: Debt Is Not Automatically a Deal-Breaker
Verdict: the size of the loan matters less than the story behind it.
A ₹25 lakh education loan with a steady repayment plan? Very normal. A ₹4 lakh credit card bill from “treating the gang” every weekend? Different conversation.
Most of us carry some debt. Home loans, car EMIs, that phone you bought on “No Cost EMI” because the ad said so.
Saying no to everyone with a loan is like saying no to everyone who has ever eaten street food. Your match list will be very short and very lonely.
It’s a lot like deciding whether to marry someone with a much lower salary than you. The number is the headline. Habits are the real story.
Not All Debt Is the Same
Before you panic, sort the loan into the right box.
Investment Debt (Usually Fine)
Education loans, home loans, a business loan for something real. These were taken to build a future.
They come with a plan, a fixed EMI and an end date. That’s adulting, not a crisis.
Family Responsibility Debt (Needs a Calm Talk)
A loan for a parent’s surgery. A sister’s wedding. Rebuilding the house in the village.
This kind of debt often shows a person who shows up for family. Respect that. But ask who is repaying it, and whether more such costs are coming. It ties straight into the joint family vs nuclear family debate, because family money and family living setups usually travel together.
Lifestyle Debt (Look Closer)
Credit cards swiped to the limit. Personal loans for iPhones, trips and designer sneakers. Buy-now-pay-later apps stacked three deep.
One bad year happens. A pattern of spending money they don’t have is the thing to watch.
Hidden or Risky Debt (Big Red Flag)
Loans from shady apps. Gambling or betting losses. Money borrowed from five friends, none of whom are being repaid.
🚩 Red flag: they only told you because you found the EMI message on their phone.
The Real Question Is Not the Number
Meet Arjun. 30. Software engineer. ₹18 lakh education loan from his US master’s.
He has a spreadsheet. He pays extra every Diwali bonus. He’ll be debt-free in three years.
Now meet Kabir. 29. Owes ₹3 lakh across four credit cards. Says “it’ll sort itself out, yaar.”
Arjun owes six times more. Who would you trust with a joint account?
Exactly.
When you think about whether to marry someone with debt, judge these three things:
- Honesty: did they tell you early, without being asked?
- Plan: do they know the exact amount, the EMI and the end date?
- Behaviour: are they still adding to it, or paying it down?
Three yeses? That’s a responsible adult with a loan. Not a problem.
Questions to Ask Before You Marry Someone With Debt
Don’t make it an interrogation. You’re not a bank manager. Ask like a future teammate.
- “How much is it, roughly, and what was it for?” You need the real number, not “kuch zyada nahi”.
- “What’s the monthly EMI, and when does it end?” This tells you how much of their salary is already spoken for.
- “Is anyone else on this loan?” Co-borrowers and guarantors (often parents) change the picture.
- “Any other loans I should know about?” Ask once, kindly. Watch the pause.
- “How do you see us handling it after marriage?” Their loan, shared effort, or a joint plan? There’s no single right answer. There is a wrong one: “I hadn’t thought about it.”
These sit nicely next to the five money questions every couple should ask. And if you’re dreading the whole chat, our list of uncomfortable questions couples avoid before marriage will show you you’re not alone.
What to say instead of “Why would you take such a big loan?”:
“Thanks for telling me. Honestly, that matters more to me than the amount. Can we look at the plan together sometime?”
Calm, kind, and still gets you the facts.
Red Flags vs Green Flags
| 🚩 Red flag | ✅ Green flag |
|---|---|
| Hid the loan until the roka was fixed | Mentioned it once things got serious |
| Doesn’t know the exact amount | Knows the amount, EMI and end date |
| Still taking new loans for gadgets | Paying extra whenever possible |
| Expects you to clear it after the wedding | Wants a fair plan you both agree on |
| Gets angry when you ask | Answers patiently, even when it’s awkward |
Notice something? Not one of these is about the amount. It’s all about behaviour. The same goes for the bigger list of red flags you should never ignore in an arranged marriage.
What Happens to Debt After Marriage?
Good news first. In India, marrying someone usually does not make you legally liable for loans they took before the wedding. Unless you sign as a co-borrower or guarantor.
Your credit score is also your own. Their old card bill won’t magically appear on your report.
The catch? Real life doesn’t care about paperwork.
- If ₹40,000 a month goes to EMIs, that’s ₹40,000 less for rent, savings and holidays.
- A new home loan together may get harder if one partner’s credit is shaky. Still deciding whether you even need to own a house before marriage? Settle that first.
- Money stress follows you into the bedroom, the kitchen and every family function.
Pro tip: don’t sign as a guarantor on any loan before the wedding. Love is blind. Banks are not.
Also, please don’t add a wedding loan on top of an existing one. A sensible wedding planning checklist for Indian weddings helps you set a budget that doesn’t need a personal loan. And skip the classic wedding planning mistakes that wreck budgets, like inviting 800 people because Sharma uncle invited 750.
A big wedding fades in one weekend. A big EMI stays for five years.
When It’s Okay to Walk Away
Sometimes the kind thing is to say no. You can step back if:
- They lied about the debt, more than once.
- There’s gambling, betting or loans from shady apps, with no real effort to stop.
- They expect you or your family to clear it as a quiet “gift”.
- Your money values are opposite and neither of you wants to budge.
Saying no to these isn’t greedy. It’s protecting your future self.
And if none of these apply? Maybe this is just a good person with an EMI. Which describes half of urban India.
In the end, only you know what you can live with. Ask the questions, look at the plan, and trust what the behaviour tells you.
Keep Reading
- Should Salary Be Discussed on the First Matrimony Call?
- Should You Reveal Your Exact Salary on a Matrimony Profile?
- When Should You Tell Your Match About Your Past Relationships?
Quick Takeaway
- Debt alone is not a deal-breaker. Honesty, a plan and current habits matter more.
- Education and home loans are usually fine. Lifestyle and hidden debt need a closer look.
- Ask the amount, EMI, end date, co-borrowers and how they see you handling it together.
- Never sign as a guarantor before the wedding.
- Walk away from lies, gambling, or “you’ll pay it off for me” energy.
FAQs
Should I marry someone with a lot of debt?
It depends on the type of debt and how they handle it. An education or home loan with a clear repayment plan is normal. Hidden debt, gambling losses or growing credit card bills are much bigger concerns.
Am I responsible for my spouse’s debt after marriage in India?
Usually not for loans taken before marriage, unless you signed as a co-borrower or guarantor. But their EMIs will still affect your shared budget, so plan for it together.
Does my partner’s debt affect my credit score?
No, credit scores are individual. Joint loans or credit cards you open together will affect both of you, so be careful before signing anything jointly.
How do I ask my match about their debt without offending them?
Thank them for being open, then ask simple questions: how much, what it was for, the EMI and the end date. Keep the tone curious, like a teammate, not a bank manager.
What kind of debt is a deal-breaker before marriage?
Debt they lied about, gambling or betting debt, and loans they expect you or your family to clear. These point to habits and honesty problems, not just money problems.
Debt can be paid off. Dishonesty is much harder to repay.
So don’t run at the word “loan”. Run at the word “later” when you ask for the details.
Know a friend whose match just confessed a “small” ₹12 lakh loan? Send this their way. And tell us in the comments: would you marry someone with debt?
Money Before Marriage: 5 Questions to Ask
October 25, 2026 at 9:15 am[…] Education loans. Car EMIs. Credit card rollovers. A sibling’s wedding they helped fund. A home loan their parents took in their name. If your match is the one carrying a big loan, here is how to decide whether to marry someone with significant debt. […]
Add a comment